France’s Crisis Looms as U.S. Faces Fiscal Challenges
France’s protests and debt crisis mirror U.S. fiscal concerns. What can be done?
3 min read
France is experiencing a growing crisis as protests erupt over rising living costs and strained public services, with millions taking to the streets. The situation, however, is not just about social unrest—it’s also a warning for the United States as both nations face similar fiscal challenges.
France’s Growing Fire
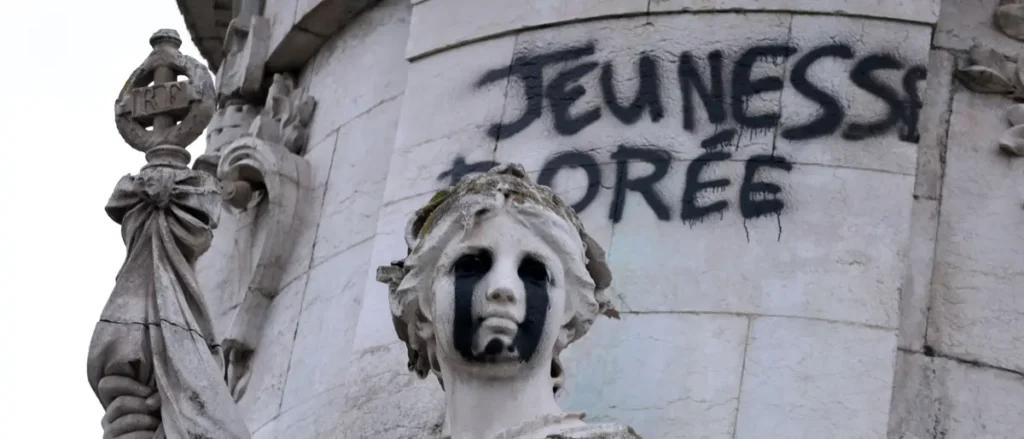
On October 17, between 550,000 and 800,000 people marched across France, marking a significant moment of public discontent. The protests followed weeks of student demonstrations that disrupted hundreds of schools. While President Trump blamed immigration for the unrest, the marchers expressed frustration over the cost of living, limited public services, and a future that feels out of reach.
The underlying issue is financial. France’s debt has reached nearly 120% of its economy, with the country spending over 74 billion euros annually just on debt servicing—more than it spends on education or defense. Borrowing costs have hit a 24-year high, and two prime ministers have fallen in under a year due to budget disputes. Governments that attempt to address the debt crisis face political backlash, making it difficult to implement meaningful reforms.
The U.S. Faces a Similar Dilemma
The U.S. is not far behind. The Congressional Budget Office projects that net interest on the national debt will double to about $2.1 trillion by 2036, consuming roughly half of every dollar the federal government collects. Currently, the U.S. spends more on interest than on national defense, and the situation is only expected to worsen.
The root of the problem is not just about the debt itself but also about the distribution of wealth. The Federal Reserve’s latest Survey of Consumer Finances found that median net worth for households headed by someone 75 or older rose by 38% from 2022 to 2025, while households headed by someone under 35 saw a 23% decline. Americans 55 and older now hold roughly $140 trillion, or about three-quarters of the nation’s net worth.
This growing wealth gap creates a challenge for the younger generation, who are expected to carry the burden of an aging population and rising interest costs. As a result, the U.S. faces a crisis of its own, with a shrinking pool of resources to meet the needs of an aging population and a struggling younger generation.
A Path Forward
The solution, according to the author, lies in long-term growth and fiscal responsibility. A country that grows faster can pay its debts, fund its promises, and give its young people a real shot at the future. This means investing in infrastructure, education, and entrepreneurship, as well as being willing to reform programs before the bond market forces the changes.
However, neither political party is offering a viable plan. One treats deficits as someone else’s problem while cutting taxes, and the other promises new spending without addressing who will pay for it. Both are counting on the crisis arriving after the next election, which could be a dangerous approach.
As the midterms approach, voters must ask candidates what their plan for growth is and what they are willing to give up to achieve it. If they cannot answer, they are not ready for what is coming. France’s crisis serves as a warning: the U.S. must act now to avoid a similar fate.
Source: Daily Caller